CARIBBEAN |Amsterdam Moved Its Gold. Caracas Still Can’t Move Its Own.
CARIBBEAN |Amsterdam Moved Its Gold. Caracas Still Can’t Move Its Own.
The Dutch central bank moved 86 tonnes of gold out of New York and Ottawa and called it a liquidity upgrade. Caracas, whose bullion has sat frozen in London since 2018, could have told Amsterdam what the real lesson is.
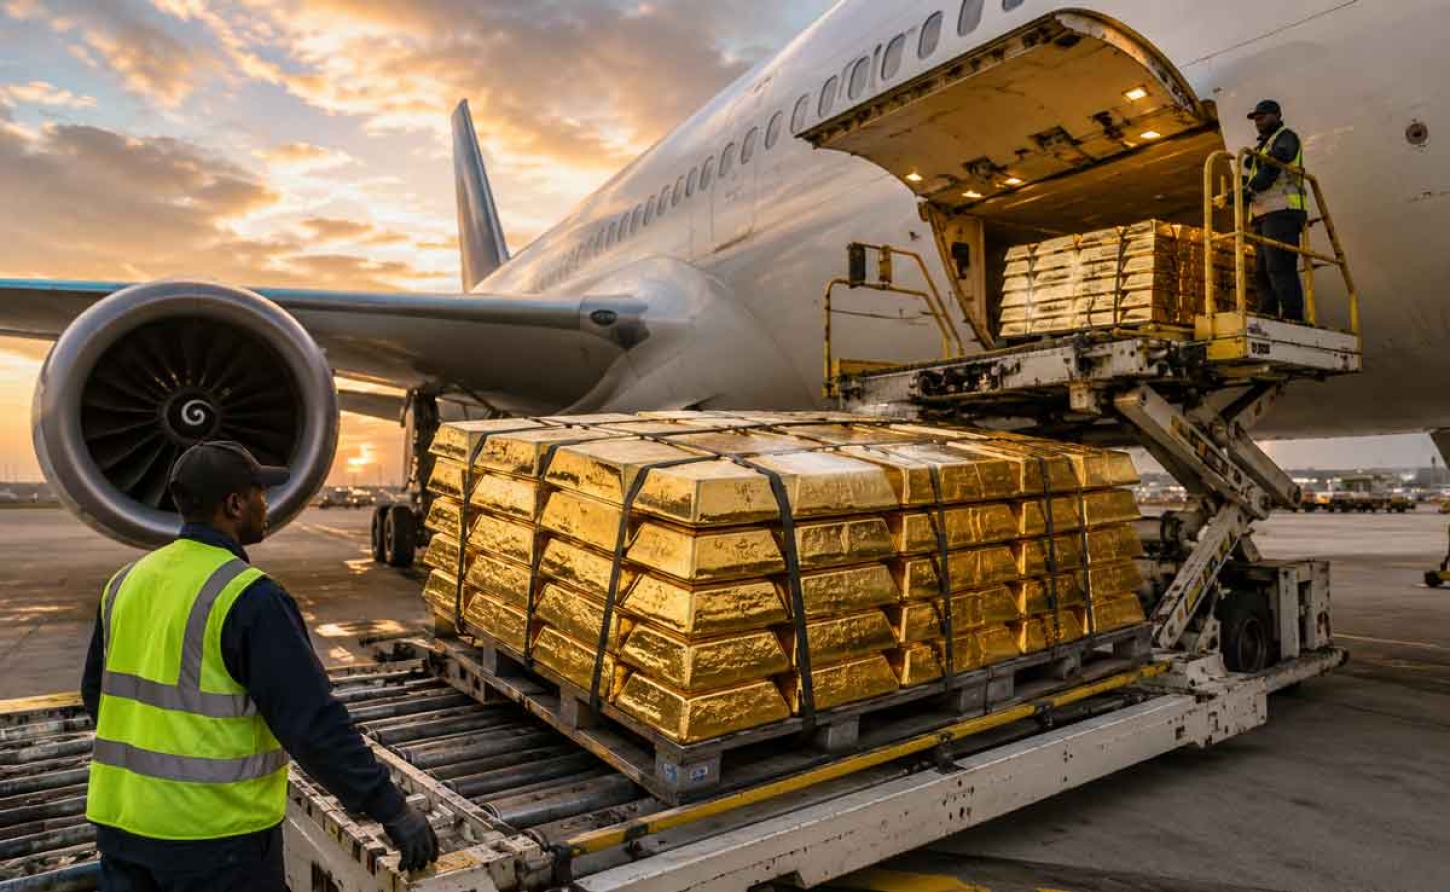
MONTEGO BAY, Jamaica, Calvin G. Brown - September 3, 2026 - De Nederlandsche Bank said it was about tradability. Between March and August the Dutch central bank shifted 86 tonnes of gold out of New York and Ottawa into the Bank of England, cutting New York’s share of the Dutch stock from 31.3 per cent to 18.5 and lifting London’s from 18.1 to 32.1. Total holdings did not change: 612.4 tonnes, worth €72.2 billion at the end of 2025. Governor Olaf Sleijpen said the move had improved the reserves’ tradability, and that the bank assumes it will never need to deploy them.
Read the statement closely, though, and the operative phrase is not tradability. DNB said the decision was taken because of increasing geopolitical unrest. That is a central bank — an institution whose entire professional register is calibrated to say as little as possible — telling the world it would rather its most fungible asset were not sitting where it has sat since Bretton Woods.
The Move Behind the Wording
The mechanics confirm the caution. Only 27 tonnes travelled physically, routed through DNB’s vault at Zeist. The remaining 59 tonnes were sold in New York and repurchased in London — a bookkeeping manoeuvre that achieves relocation without a fleet of aircraft or a diplomatic incident. And 18.5 per cent of Dutch gold stays in New York. This is a hedge, not a rupture, and honesty requires saying so: nothing in DNB’s conduct suggests it believes the Federal Reserve is about to steal anything.
But markets read gestures, not disclaimers. UBS economist Paul Donovan called the move “not normal behavior.” The direct market impact is nil — the gold is still gold, and London gold still trades in dollars — but the signals about trust in the United States are, he judged, quite dramatic.
Donovan set the timing against Treasury Secretary Scott Bessent’s intervention to support the yen, reportedly meant to stop Japanese investors bolting from the Treasury market. While Washington held one door shut, Amsterdam slipped out another. American national debt passed US$40 trillion weeks ago.
What Caracas Already Knew
Here the Caribbean has standing to speak, because the region has already watched this film. Roughly 31 tonnes of Venezuelan gold has sat in the Bank of England’s vaults since 2018, when Britain stopped recognising the Maduro government and the bullion became the subject of litigation still unresolved.
That is about two-thirds of Venezuela’s reported monetary gold stock of 47 tonnes. It appears on the central bank’s balance sheet. It cannot be touched.
In August, after the June earthquakes that killed more than 6,000 people, the government and sectors of the opposition did something they have not managed in years and issued a joint appeal for the gold’s release to fund reconstruction.
The Foreign Office replied that Britain is not a party to the court case. The Bank of England, custodian to a great many developing nations, still holds the bars.
For Amsterdam, London means liquidity. For Caracas, London has meant title without access — which is another way of saying bookkeeping.
So the asset the Dutch have relocated for safekeeping is the same asset a Caribbean neighbour cannot retrieve to bury its dead. The Netherlands has not escaped jurisdictional risk; it has changed jurisdictions, from one power that has frozen sovereign reserves to another that has done the same.
The difference is not the vault. It is that Amsterdam expects to stay on good terms with its custodian, and Caracas does not.
The 2022 Recalculation
The underlying shift began when roughly US$300 billion of Russian central bank reserves were immobilised in Western institutions in 2022. Every reserve manager holding assets abroad did the arithmetic.
Foreign central banks now hold about US$4.5 trillion in gold against roughly US$3.5 trillion in American government bonds; gold overtook Treasuries as the world’s largest reserve asset this year for the first time since 1996. The World Gold Council’s 2026 survey found 74 per cent of reserve managers expecting the dollar’s share of reserves to fall within five years.
The Netherlands is not first. The Banque de France sold 129 tonnes in New York in March and bought in Europe, framing it as a bar-purity upgrade rather than a political statement. India has repatriated 274 tonnes since 2023.
The New York Fed’s foreign gold, above 12,000 tonnes at its 1973 peak, is now near 6,331. Germany is the number that matters: 1,236 tonnes there, close to a fifth of all foreign gold in the vault, and the Bundesbank insists the arrangement stands.
The analyst John Plassard called the Dutch decision fairly one-off while warning that a wave of them would corrode confidence in American custody. Whether Berlin holds its nerve is the story to watch.
The View From Where We Sit
CARICOM has no gold to move. Regional reserves are overwhelmingly dollars and United States Treasuries, and the region’s monetary plumbing runs through correspondent banking relationships it does not own — as the de-risking wave taught, when global banks withdrew and the region learned that dollar access is a privilege extended, not a right held. Advanced economies are now insuring against exactly that exposure.
Small open economies carrying dollar debt, importing food and fuel and pricing tourism receipts in dollars will absorb the volatility without the hedge.
There is one honest upside: sustained official-sector demand underwrites the gold price, near US$4,400 an ounce this week, and that flows into Guyanese and Surinamese mining revenue. It is a producer’s consolation, not a reserve manager’s.
The unspoken part of the Dutch move is not that America has become untrustworthy. It is that trustworthiness has become conditional, and that every state is now quietly pricing the condition. Caribbean governments should read the pricing carefully. Sovereignty that runs entirely through another nation’s vaults, wires and correspondent banks is sovereignty on loan, and the terms are always set elsewhere.
— 30 —